New York Is Closing the Gap on California’s Film and Television Production Spending
By DaMarko GianCarlo
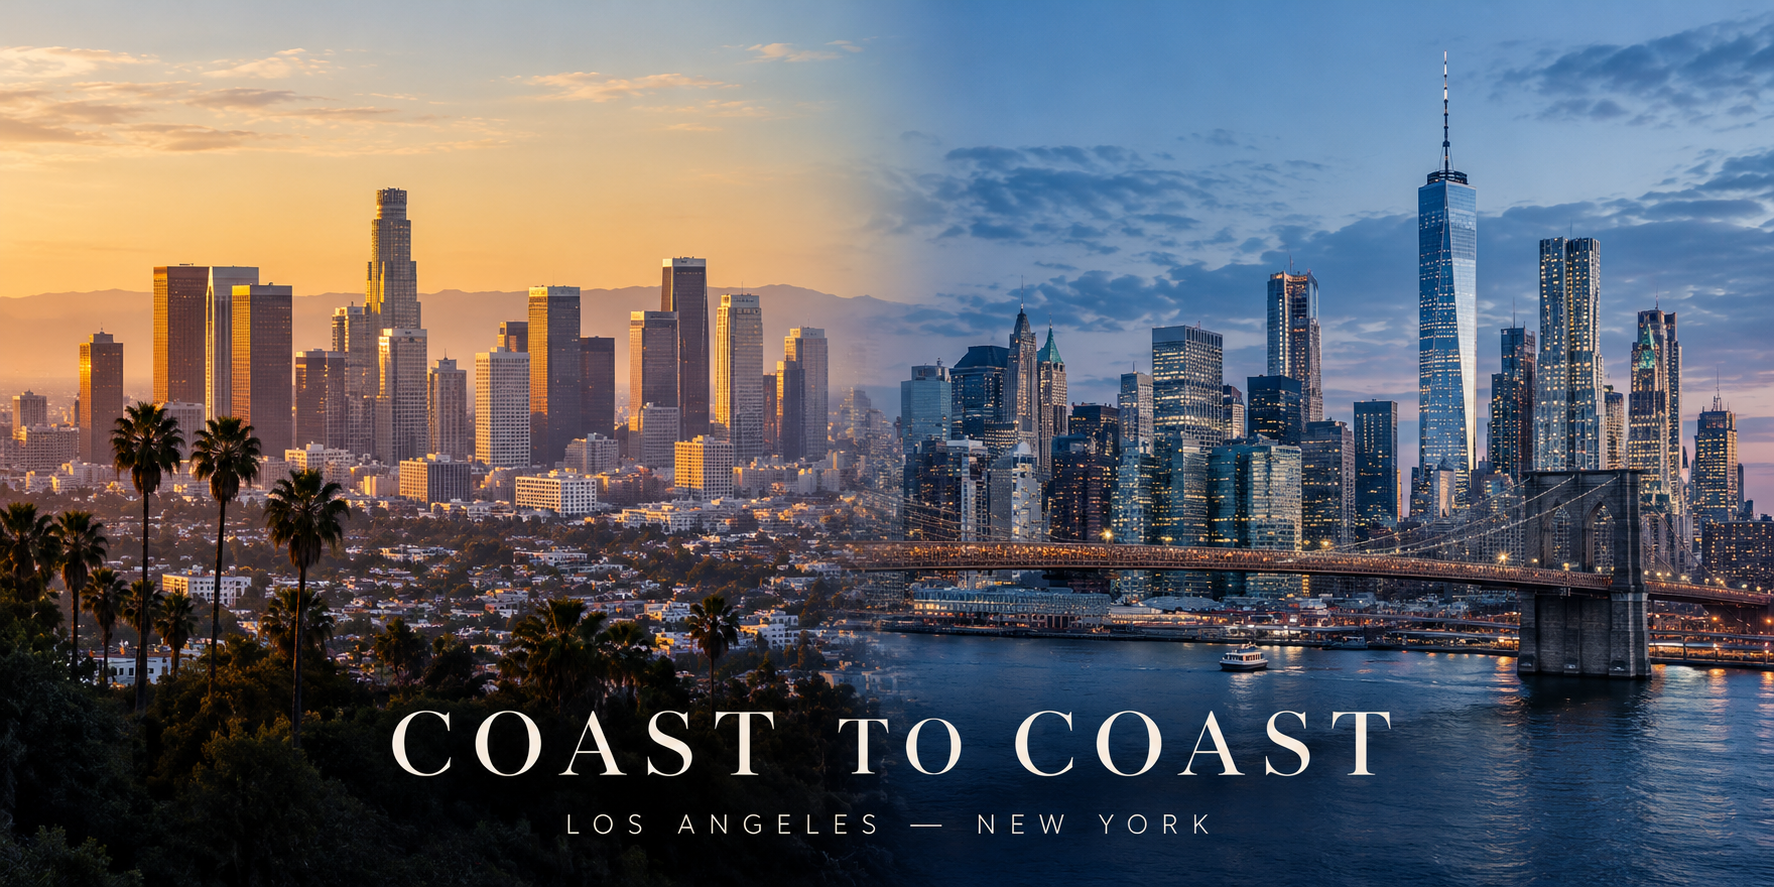
California remains the largest film and television production market in the United States by estimated quarterly spending, but New York is narrowing the difference. New industry figures show production spending increasing in both states during the third quarter of 2026, with New York recording a considerably faster rate of growth. The results reflect a competitive environment in which production incentives, available studio space, returning television series, and established workforces are influencing where projects are made. They also raise a broader question about how the industry’s recovery should be measured beyond the amount of money spent.
According to industry tracking company ProdPro, California generated approximately $1.76 billion in film and television production spending during the third quarter of 2026, an increase of 17 percent compared with the same period a year earlier. New York recorded approximately $1.61 billion, representing an 87 percent year-over-year increase. California retained its lead by approximately $147 million, according to figures reported by The Hollywood Reporter. The estimates measure production spending during a specific quarter rather than the overall size or economic value of either state’s entertainment industry.
New York’s growth was already evident earlier in the year. During the second quarter, California recorded approximately $1.33 billion in production spending compared with New York’s $1.06 billion, leaving a difference of roughly $270 million. By the third quarter, that gap had narrowed considerably. New York recorded stronger year-over-year growth in both periods, indicating that its increased spending was not limited to a single quarter. Whether that momentum continues will depend on subsequent production activity and the projects entering each market.
An important part of New York’s production business is its established television industry. Long-running scripted series such as Law & Order: Special Victims Unit and FBI maintain production operations that support recurring demand for crews, equipment, locations, and other services. While feature films can bring substantial spending into a region during a concentrated production period, returning television series can provide repeated work across successive seasons. The economic contribution of these productions depends on the number of episodes commissioned, the length of their shooting schedules, and whether they continue operating in the region.
New York’s ability to accommodate larger productions has also expanded. In June, commercial real estate services firm CBRE reported that soundstage inventory across the New York Tri-State region had increased by 43 percent since 2020. The expansion includes purpose-built facilities designed to accommodate major film and television projects, giving producers more options when considering where to establish production operations. The regional distinction is important because the figures include studio development beyond New York State, reflecting a production market that extends across state boundaries.
CBRE also found that the Tri-State region was the only major American production market where production starts had recovered to levels recorded before the 2023 Hollywood labor disputes. Employment, however, had not recovered at the same pace. Regional motion-picture employment remained at approximately 86 percent of pre-pandemic levels. These findings demonstrate that increased production activity and employment recovery are separate measures. A higher number of productions or greater overall spending does not necessarily correspond to an equivalent increase in the number of people working.
Government incentives are another established part of the competition. New York’s Film Production Tax Credit Program offers qualifying productions a base credit of 30 percent on eligible expenses, supported by an annual program allocation of $700 million through 2036. Additional provisions apply to certain productions and locations. These incentives can reduce qualifying production costs and influence budget considerations, although the existence of a tax credit alone does not establish why an individual studio or producer selects a particular location.
California has expanded its own financial commitment to production. In 2025, the state increased the annual allocation for its Film and Television Tax Credit Program to $750 million. During the fiscal year ending June 30, 2026, the California Film Commission approved 170 projects representing a projected $6.6 billion in direct production spending and approximately 34,900 cast and crew jobs. Those figures represent anticipated economic activity associated with approved projects, rather than completed spending or confirmed employment. They nevertheless demonstrate the extent of California’s efforts to retain existing productions and attract additional projects.
California’s statewide spending growth is particularly important when considered alongside production conditions in Los Angeles. On October 21, FilmLA reported 4,171 on-location shoot days across Greater Los Angeles during the third quarter of 2026, a decline of 4.8 percent compared with the same period in 2025. Activity was also nearly 29 percent below the five-year average. Productions participating in California’s film and television tax-credit program accounted for 40.3 percent of scripted on-location filming, nearly twice their share a year earlier.
The FilmLA and ProdPro findings are not contradictory. FilmLA measures permitted on-location filming activity within the Greater Los Angeles region, while ProdPro estimates a broader category of production spending across California. A production working primarily on soundstages may generate substantial spending without producing the same volume of permitted location filming. Similarly, an increase in the cost or size of individual projects can affect spending totals without producing a comparable increase in filming days. Each measurement captures a different aspect of the industry’s activity.
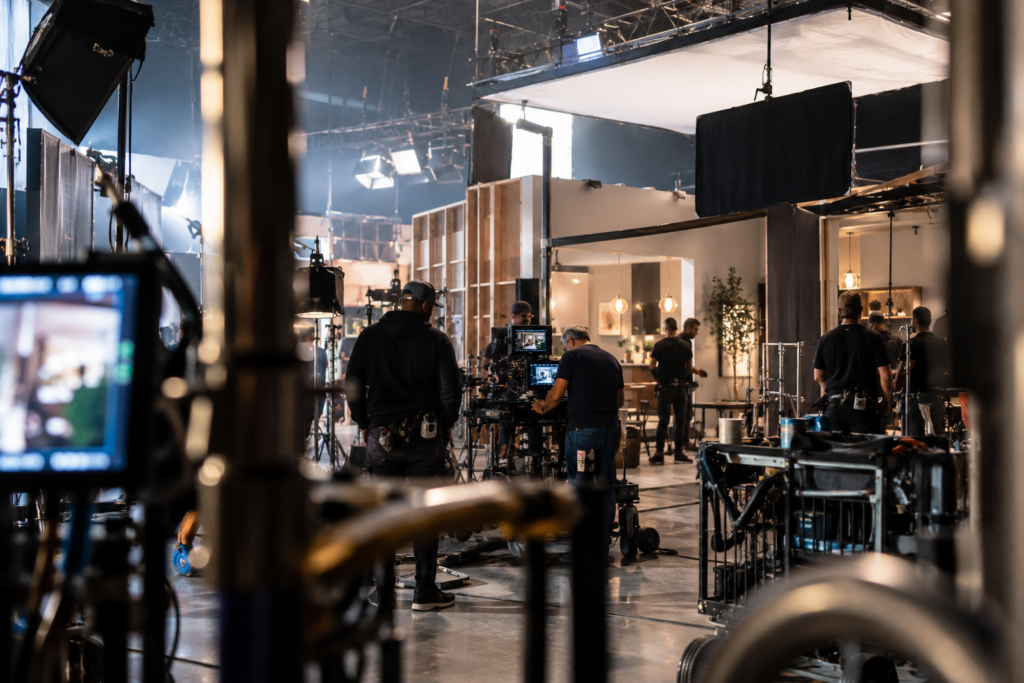
These distinctions are significant for the workforce supporting film and television production. Camera crews, set builders, electricians, makeup artists, drivers, production assistants, and other professionals depend on the volume, frequency, and duration of available work. Spending figures can indicate the financial size of production, but employment levels and production schedules provide additional information about how that activity reaches workers. A comprehensive assessment of the industry’s recovery requires examining those measures together rather than treating one as a substitute for another.
New Jersey is also contributing to the expansion of production capacity in the Northeast. Major developments include Netflix’s planned production campus at Fort Monmouth, 1888 Studios in Bayonne, and the Lionsgate-associated studio project in Newark. These facilities are part of a broader effort to establish permanent production operations within reach of the New York metropolitan workforce. New Jersey also maintains its own film incentive program, generally offering qualifying productions credits ranging from 30 to 35 percent on eligible expenses, depending on location and applicable requirements.
The relationship between New York and New Jersey illustrates how production markets can operate regionally even when economic activity is measured by individual states. Productions may draw from overlapping labor markets, equipment suppliers, and specialized services while evaluating different facilities and incentive programs. Spending attributed to New Jersey, however, remains separate from New York’s state totals. Planned studio developments also cannot be counted as completed production activity until facilities become operational and attract projects.
New Jersey’s recent performance demonstrates why additional capacity should not be interpreted as a guarantee of continued growth. Despite increases in production spending earlier in 2026, the state’s filming count declined during the third quarter compared with the previous year. The development of new facilities may improve its ability to compete for future projects, but their longer-term economic contribution will depend on occupancy, production schedules, and sustained demand.
The competitive environment extends beyond the Northeast and California. Georgia, Illinois, and other states continue to participate in the American production market through their own incentives, facilities, and established workforces. ProdPro estimated approximately $4.9 billion in total United States film and television production spending during the third quarter of 2026, representing a 17 percent year-over-year increase. California and New York accounted for a substantial majority of that estimated spending, underscoring their continued importance even as other states seek additional production investment.
These regional developments are unfolding as the entertainment business continues adjusting to changes in television commissioning, streaming economics, and production budgets. Studios and distributors determine not only which projects move forward, but also how much capital they allocate and where those projects can be produced. State incentives and available facilities can influence those decisions, but they operate alongside creative requirements, scheduling, labor availability, and the financial circumstances of individual productions.
The latest spending figures establish that New York has become more competitive with California, but they do not establish a permanent change in industry leadership. California continues to attract substantial production investment, and its third-quarter spending increased despite the decline in permitted on-location filming reported in Los Angeles. New York’s growth is significant, supported by an established television business and expanding regional production capacity, but future results will determine whether its recent gains represent a lasting shift.
As the industry moves toward 2027, quarterly spending rankings will remain useful indicators of where production money is being directed. Their meaning will become clearer when considered alongside employment, production starts, returning projects, and soundstage utilization. These measures will help distinguish short-term increases in activity from sustained changes in the production business.
For now, the competitive position of the two states is clear. California remains the national leader in estimated film and television production spending, while New York has substantially narrowed the gap. The available evidence shows an industry in which both markets are attracting increased spending, even as individual regions and workers experience different rates of recovery. Whether New York ultimately surpasses California remains to be determined by future production activity, not the momentum of a single reporting period.
Related Posts
Dream Con Shows What Creator-Led Culture Looks Like in Real Life
A Weekend Built on Years of Connection
The Body Is the Interface Now
Sneakers are no longer worn — they are programmed
FIFA Is Redefining What a Broadcaster Looks Like
Distribution Beyond Television
Ralph Lauren Is Bringing PoloFest to Tokyo to Celebrate a Culture That Has Thrived for Decades
Ralph Lauren Created the World. Communities Gave It New Meaning.
Wendy Braun Never Stopped Becoming
A life shaped by movement, reinvention, and belief
The Rainmaker Returns: A Grisham Classic Finds New Life on TV
New Firm. Old Rules. Deadly Secrets.
POST COMMENT